Implied Volatility in Options Trading: How It Works
Imagine buying travel insurance right before a severe monsoon storm is forecast to hit your coastal city. Insurers raise their rates because the chance of sudden disruption increases, and once the storm passes, those rates drop back down.
In options trading, implied volatility works on that exact risk-pricing principle. Whenever traders anticipate sharp price swings in underlying assets like Nifty 50 or Bank Nifty, option premiums expand. Understanding how IV in options behaves helps you evaluate whether a contract’s price reflects elevated market uncertainty or calm trading conditions before you open a position.
Quick Takeaways
- Implied volatility (IV) reflects the market’s forward-looking forecast of an underlying asset’s annualized price fluctuation, derived directly from live option premiums.
- Rising IV increases extrinsic value for both Call and Put contracts regardless of market direction, while falling IV shrinks option prices.
- Because IV often drops sharply right after scheduled announcements like corporate earnings, option buyers face the risk of “IV crush” even when they correctly predict price direction.
What Is Implied Volatility in Options Trading?
Implied volatility is the stock market’s forward-looking estimate of how much an underlying asset’s price may fluctuate over a year, calculated from current option prices.
When you look up what implied volatility means in derivatives markets, it helps to separate direction from magnitude. IV does not indicate whether an index or stock will rally or fall. Instead, it measures the expected size of the price movement priced into the option contract.
Market makers and traders determine option prices using mathematical frameworks such as the Black-Scholes model. While inputs like the underlying price, strike price, interest rate, and days to expiration are known, future volatility is unknown. Pricing models work backward from the live market premium to solve for the volatility figure that justifies that price.
When major events approach—such as quarterly earnings, Reserve Bank of India (RBI) policy meetings, or the Union Budget—demand for option contracts typically rises. Higher demand pushes up option premiums, which translates into higher IV readings across the market.
Tip: Think of IV as a real-time gauge of market uncertainty rather than a directional price signal.
Implied Volatility vs. Historical Volatility: Key Differences
Implied volatility measures expected future price swings priced into option contracts, whereas historical volatility (HV) measures actual past price fluctuations over a completed lookback period.
Comparing both metrics helps traders see whether current option premiums are pricing in more or less movement than the asset has recently delivered. If a stock’s 30-day HV sits at 14% while its current IV climbs to 26%, the derivatives market is pricing in an upcoming catalyst that could trigger wider swings than usual.
| Feature | Implied Volatility (IV) | Historical Volatility (HV) |
|---|---|---|
| Time Horizon | Forward-looking (expected future movement) | Backward-looking (actual past movement) |
| Calculation Source | Derived from live option contract premiums | Computed from historical closing prices |
| Primary Role | Reflects current supply, demand, and event risk | Establishes a baseline of typical price behavior |
| Sensitivity to News | Spikes ahead of scheduled events and drops afterward | Changes only after actual price swings occur |
Neither metric guarantees future performance. Historical volatility can remain quiet right before an unexpected breakout, while elevated IV can overstate actual post-event movement.m will gain or lose for every 1% change in implied volatility, assuming underlying price and days to expiration remain constant.
How Implied Volatility Affects Option Premiums and Vega
Higher implied volatility increases the extrinsic (time) value of both Call and Put options, making contracts more expensive for buyers and increasing upfront credit for sellers.
Option premiums consist of intrinsic value and extrinsic value. Because IV reflects uncertainty about future price swings, an increase in IV directly expands extrinsic value across strike prices. In options analytics, how Vega measures volatility sensitivity quantifies this exact relationship within the broader Option Greeks framework.
Vega tells you how many rupees an option’s premium is expected to gain or lose for every 1 percentage point change in IV, assuming the underlying price and days to expiration stay constant.
Formula: Estimated Premium Change = Vega × Change in Implied Volatility (in percentage points)
Worked Hypothetical Example:
- Suppose a Nifty 50 Call option trades at a hypothetical premium of ₹120 with an IV of 14% and a Vega of ₹8.
- Ahead of a scheduled economic announcement, market demand rises and IV increases by 3 percentage points to 17%.
- Using the formula (₹8 × 3 = ₹24), the option’s extrinsic value increases by ₹24, lifting the hypothetical premium to ₹144 even if the Nifty 50 index level has not moved.
Because IV shifts affect buyers and sellers in opposite ways, each side faces distinct trade-offs:
| Market Condition | Option Buyer (Long) | Option Seller (Short / Writer) |
|---|---|---|
| Rising / High IV | Pays higher upfront premiums; benefits if IV expands further before exit | Collects larger extrinsic premiums; benefits if IV contracts toward average levels |
| Falling / Low IV | Enters at lower cost; faces premium erosion if IV drops further | Collects smaller premiums; faces sharp mark-to-market losses if volatility spikes |
| Key Risk Exposure | Premium decay from post-event volatility contraction | Unlimited or severe losses during sudden directional gaps |
What Is IV Crush? A Hypothetical Earnings Example
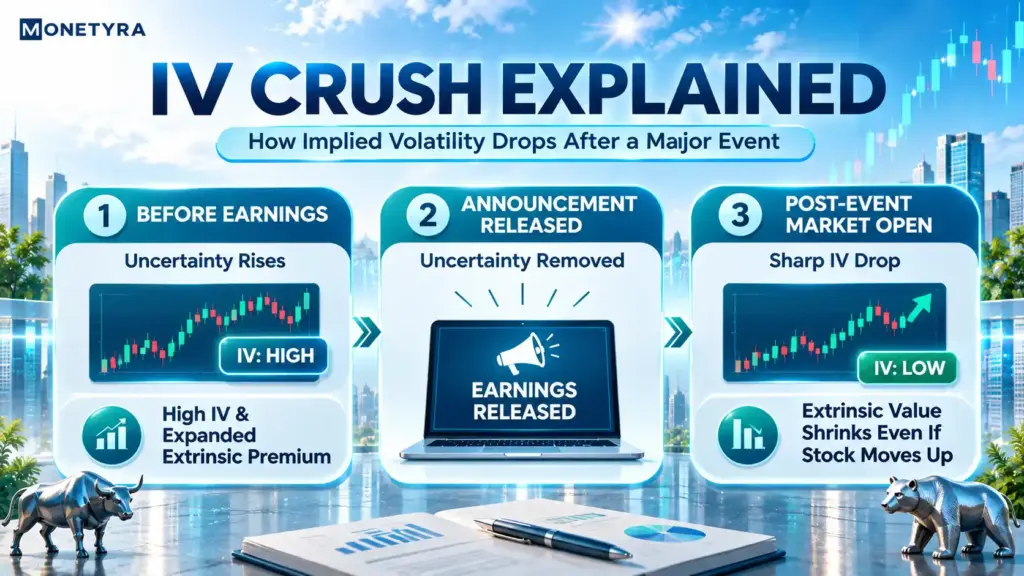
An IV crush occurs when elevated implied volatility drops abruptly immediately after a scheduled market event resolves, causing option premiums to lose extrinsic value rapidly.
Ahead of corporate earnings or policy announcements, uncertainty drives option premiums higher. Once the news becomes public, that specific uncertainty disappears, and IV often reverts to its normal baseline within minutes of the market opening.
Hypothetical Earnings Walkthrough:
- Before Results: A stock trades at ₹1,000 ahead of quarterly earnings. A trader buys an at-the-money Call option for ₹50, inflated by an elevated IV of 45% and a Vega of ₹1.50.
- Results Announced: The company reports solid numbers, and the stock opens the next morning 2% higher at ₹1,020.
- Post-Event IV Drop: With earnings uncertainty gone, IV drops by 20 percentage points to 25%.
- Net Impact: Although the stock gained ₹20, the 20-point IV drop erodes ₹30 of extrinsic value (20 × ₹1.50). After accounting for the stock’s move and time decay, the option premium falls from ₹50 to roughly ₹32, leaving the buyer with a net loss despite predicting the upward direction.
Warning: Holding long option positions across major scheduled announcements exposes your capital to rapid extrinsic value loss once uncertainty clears.
How to Read IV Rank and IV Percentile (Is 20% or 80% IV High?)
Whether an IV reading of 20% or 80% is considered high depends entirely on the underlying asset’s own historical volatility range rather than a universal benchmark.
A steady large-cap index like the Nifty 50 might typically trade between 10% and 22% IV, making 20% relatively elevated. Conversely, a mid-cap stock ahead of a regulatory verdict might range between 45% and 95% IV, making 80% normal for that specific counter.
To judge relative IV objectively, traders use two standardized metrics over a 52-week (one-year) lookback period:
- IV Rank (IVR): Measures where current IV sits relative to its highest and lowest points over the past year.
- Formula: IV Rank = [(Current IV − 52-Week Low IV) ÷ (52-Week High IV − 52-Week Low IV)] × 100
- IV Percentile (IVP): Measures the percentage of trading days over the past year on which IV closed lower than its current level.
Worked Hypothetical Example (Interpreting 20% vs. 80% IV):
- Stock A (20% Current IV): Over the past 52 weeks, Stock A recorded a low IV of 10% and a high IV of 22%. Its IV Rank is [(20 − 10) ÷ (22 − 10)] × 100 = 83.3%. Here, 20% IV is near the top of its annual range.
- Stock B (80% Current IV): Over the past 52 weeks, Stock B recorded a low IV of 50% and a high IV of 120%. Its IV Rank is [(80 − 50) ÷ (120 − 50)] × 100 = 42.9%. Despite the large headline number, 80% IV sits below the midpoint of Stock B’s annual range.
Comparing IV Rank and IV Percentile alongside fundamental catalysts prevents you from misjudging an option’s relative price based on raw percentages alone.
Reading Implied Volatility in an Option Chain and India VIX
When reading an option chain table on the National Stock Exchange (NSE), you will see a dedicated IV column displayed next to each Call and Put strike price as an annualized percentage.

Reviewing IV across strikes reveals two practical market details:
- Strike-by-Strike Skew: Out-of-the-money Put strikes in equity indices frequently display higher IV than equidistant Call strikes because institutional participants buy Puts to hedge downside portfolio risk.
- Expiry Comparison: Near-term weekly contracts often show sharper IV swings around upcoming news than monthly contracts expiring further out.
For a broader view of market-wide sentiment, traders also monitor the India VIX volatility index, which measures expected 30-day annualized volatility for the Nifty 50 index. While India VIX summarizes overall benchmark expectations, individual option chain IVs reflect supply and demand for specific strikes and expiries.
Derivatives trading in India operates under regulations set by the Securities and Exchange Board of India (SEBI). Under guidelines from the Income Tax Department, profits and losses from F&O trading are treated as non-speculative business income.
Monetyra’s Take
Implied volatility helps option traders avoid judging contract prices in isolation, as a ₹100 premium carries very different risk depending on whether IV sits near its annual highs or lows. However, relying solely on IV Rank without checking the calendar for upcoming corporate announcements or central bank decisions can leave both buyers and sellers exposed to sudden volatility shifts.
Conclusion
Implied volatility translates market uncertainty into measurable option pricing, showing how much movement traders anticipate over a given period. By comparing IV against historical volatility, evaluating IV Rank, and accounting for Vega and IV crush around scheduled events, you can better understand the risk built into every contract. Reviewing both strike-level IV in the option chain and broader benchmarks like India VIX gives you clearer context before committing capital.
Explore Futures and Options Guides
Build a stronger foundation in option Greeks, option chain analysis, and derivatives mechanics for Indian markets.
FAQs
1. What is implied volatility in options trading?
Implied volatility is the market’s forward-looking forecast of how much an underlying asset’s price may fluctuate over a year, derived from current option premiums. Unlike historical volatility, which tracks past price changes, IV reflects real-time supply, demand, and uncertainty surrounding upcoming market events.
2. How is implied volatility different from historical volatility?
Implied volatility estimates future expected price movement based on live option prices, whereas historical volatility measures actual past price swings using historical closing data. Traders compare both figures to see whether current option premiums price in wider or narrower swings than recent market behavior.
3. Is 20% or 80% implied volatility considered high?
Neither 20% nor 80% is universally high or low because normal volatility varies by asset. A 20% IV can be elevated for a stable index like the Nifty 50, while an 80% IV might be average for a volatile individual stock. Traders use IV Rank to compare current IV against its 52-week range.
4. What happens during an IV crush?
An IV crush occurs when elevated implied volatility drops sharply right after a major scheduled event, such as corporate earnings or a policy announcement. Because uncertainty disappears once the news is out, extrinsic option value shrinks rapidly, which can reduce option premiums even if the underlying asset moves in your favor.
5. How does India VIX relate to implied volatility?
India VIX is a benchmark index published by the NSE that measures expected 30-day annualized volatility for the Nifty 50 index. While India VIX reflects overall market sentiment, individual option chain IV figures measure expected volatility for specific strike prices and expiration dates.
Disclaimer: This article was written with the help of AI and edited by the Monetyra editorial team. It is for educational purposes only and should not be considered financial advice. Trading and investing in financial instruments involve significant risk of loss and are not suitable for all investors, and past performance of any strategy does not guarantee future results. Please consult a licensed financial advisor before making any investment or trading decision.
In India, derivatives trading is regulated by SEBI. Readers are advised to verify the regulatory status of their broker and ensure compliance with applicable Indian laws before investing.